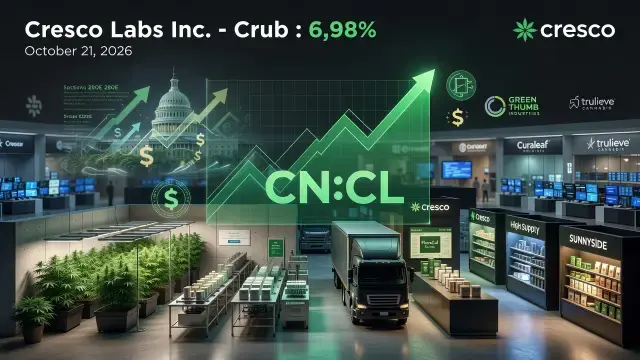
Cresco Labs Inc. (CN:CL) shares climbed 6.98% on October 21, 2026, a move that stood out even against the backdrop of a sector prone to sharp daily swings. No single press release explains the jump. What's more plausible is that investors are stitching together several threads - improving financial results, retail footprint expansion, and lingering speculation around federal cannabis reclassification - into a more constructive view of the multi-state operator's prospects.
What's Actually Driving the Setup
Cresco runs a vertically integrated operation: cultivation, processing, manufacturing, wholesale distribution, and retail, all under one roof. That structure matters more than it might sound. In cannabis, where interstate commerce remains federally prohibited, vertical integration is less a strategic flourish and more a survival mechanism - it lets an operator control cost and quality from seed to shelf without relying on a fragmented, state-by-state supply chain. Cresco's brand portfolio, including Cresco, High Supply, FloraCal Farms, and Good News, feeds both its own Sunnyside dispensaries and wholesale menus sold to third-party retailers.
The company's latest quarter showed higher revenue and improved adjusted operating earnings, and dispensary additions in Ohio and Pennsylvania have widened consumer access in two markets that are still maturing regulatory frameworks. A new revolving credit facility adds liquidity, which matters a great deal for an industry where traditional bank financing remains scarce and working capital often gets tied up in compliant inventory sitting in a budroom or warehouse awaiting lab testing clearance.
The 280E Question Still Looms Large
Here's the mechanism investors are really watching: Section 280E of the federal tax code bars cannabis businesses from deducting ordinary business expenses because the plant remains a Schedule I substance. That single rule has quietly throttled profitability across the entire multi-state operator class for years. Rescheduling - if it happens - could materially change the tax treatment of qualifying medical cannabis activity, freeing up cash that currently disappears into oversized federal tax bills. That's the structural reason reclassification news moves cannabis equities more than almost anything else in the sector. Fair enough to be skeptical, though - rulemaking timelines in Washington have a long history of disappointing anyone who bets on a fixed date.
Risks That Don't Disappear With Good Earnings
Price compression remains a persistent problem in mature markets, where wholesale pricing has fallen as cultivation capacity outpaces demand. Competitors including Green Thumb Industries, Curaleaf Holdings, and Trulieve Cannabis are fighting for the same shelf space and the same wholesale accounts, and that competitive pressure doesn't ease just because federal policy shifts. Operational execution - inventory management, compliance logging through state seed-to-sale systems, retail integration after an acquisition - carries its own risk independent of any tax reform. Debt servicing obligations add another layer; refinancing conditions in cannabis remain tighter than in most conventional retail sectors, given limited access to traditional lenders.
What to Watch Next
- November earnings release, expected to show trends in operating margin and cash generation
- Whether retail expansion in Ohio and Pennsylvania translates into sustained foot traffic rather than a short-term bump
- Progress, or lack of it, on federal rescheduling and its tax implications under 280E
- Wholesale pricing trends across Cresco's core state markets
None of this amounts to a guaranteed turnaround. Cresco's picture is cautiously constructive, not triumphant - improving fundamentals paired with real regulatory and competitive uncertainty. For operators, suppliers, and investors watching the multi-state operator space, the company's next quarterly report will tell a more reliable story than a single trading session ever could.